Primary Source Verification
Every factual data point, code release, and regulatory filing cited is independently cross-referenced against original blockchain logs and public institutional disclosures.
Verified Research Desk Verified Topic Hub
Short Liquidations: Architecture, Governance & Market Dynamics
Source-linked reporting and research about Short Liquidations, including market context, technical details and documented risks.
Every factual data point, code release, and regulatory filing cited is independently cross-referenced against original blockchain logs and public institutional disclosures.
Analysis separates promotional marketing claims from verifiable transaction settlement, smart contract events, and transparent liquidity movements.
Detailed examination of private key management, smart contract access controls, multisig governance, and potential counterparty failure points.
Coverage contextualizes technological innovation within jurisdictional licensing boundaries, anti-money laundering mandates, and financial disclosure standards.
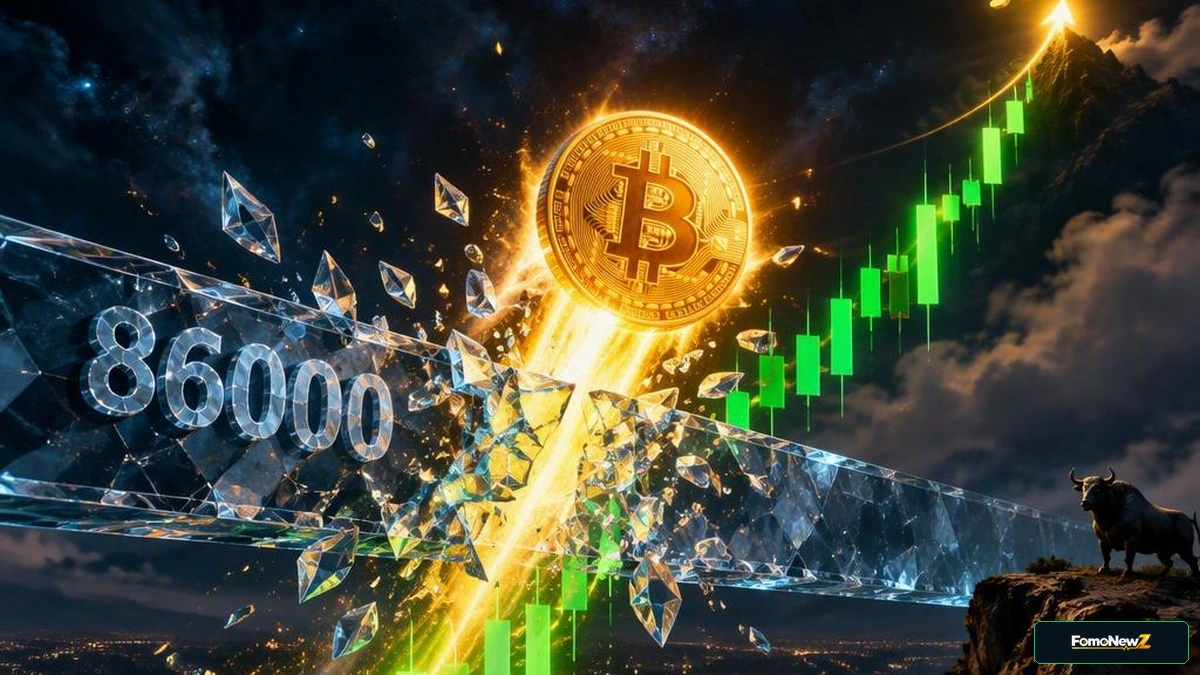
Bitcoin surged 7.14% to clear $86,633, obliterating over $120 million in short positions and sparking an aggressive race toward the $90,000 psychological milestone.
As Saudi Arabia exits the mBridge platform, wholesale institutional liquidity is aggressively hunting neutral enterprise rails. The XRP Ledger emerges as a primary beneficiary amid shifting global settlement architectures.
Bitmine's $75 million ether acquisition highlights surging institutional demand. However, this massive corporate inflow is testing Ethereum's consensus limits.
Circle's new Bitcoin-backed USDC borrowing service allows corporate treasuries to secure dollar credit without selling assets. This structural shift locks up circulating supply, accelerating BTC's supply squeeze.
A headline quote represents only the most recent marginal trade size. Order book depth measures the aggregate volume of limit buy and sell orders queued within 1% and 2% price bands. In thin markets, executing a modest order sweeps through resting levels, resulting in execution prices significantly worse than quoted.
AMMs rely on the constant product formula (x · y = k). When a swap removes a significant percentage of a token from the liquidity reserve, the relative ratio shifts non-linearly along the pricing curve, forcing the trader to receive fewer tokens than estimated before the transaction was submitted.
Impermanent loss occurs when the price ratio of pooled tokens diverges from when they were deposited. The AMM rebalances the pool by selling the appreciating token and accumulating the depreciating one, leaving the liquidity provider with lower dollar value than if they had simply held the individual assets in cold storage.
Maker orders (limit orders) provide liquidity to the order book without executing immediately, allowing other traders to trade against them. Taker orders (market orders) execute instantly against resting limit orders, consuming existing depth and paying higher trading fee tiers.
Professional market making firms deploy low-latency algorithmic trading engines across multiple centralized and decentralized venues. During extreme market volatility, algorithms widen quotation spreads and pull resting bid size to protect inventory from toxic informed flow, temporarily thinning available liquidity across the market.