Chapter 01
Debit, Prepaid, and Collateralized Credit Models
Crypto payment cards enable consumers to spend digital assets at millions of traditional merchants worldwide by connecting blockchain liquidity with card payment rails like Visa and Mastercard.
However, crypto cards do not all operate on the same financial architecture. Three primary models exist in the market:
- Prepaid Crypto Cards: The user manually sells crypto assets inside an exchange or wallet app to fund a conventional fiat currency balance (USD, EUR, GBP) before tapping the card at a payment terminal.
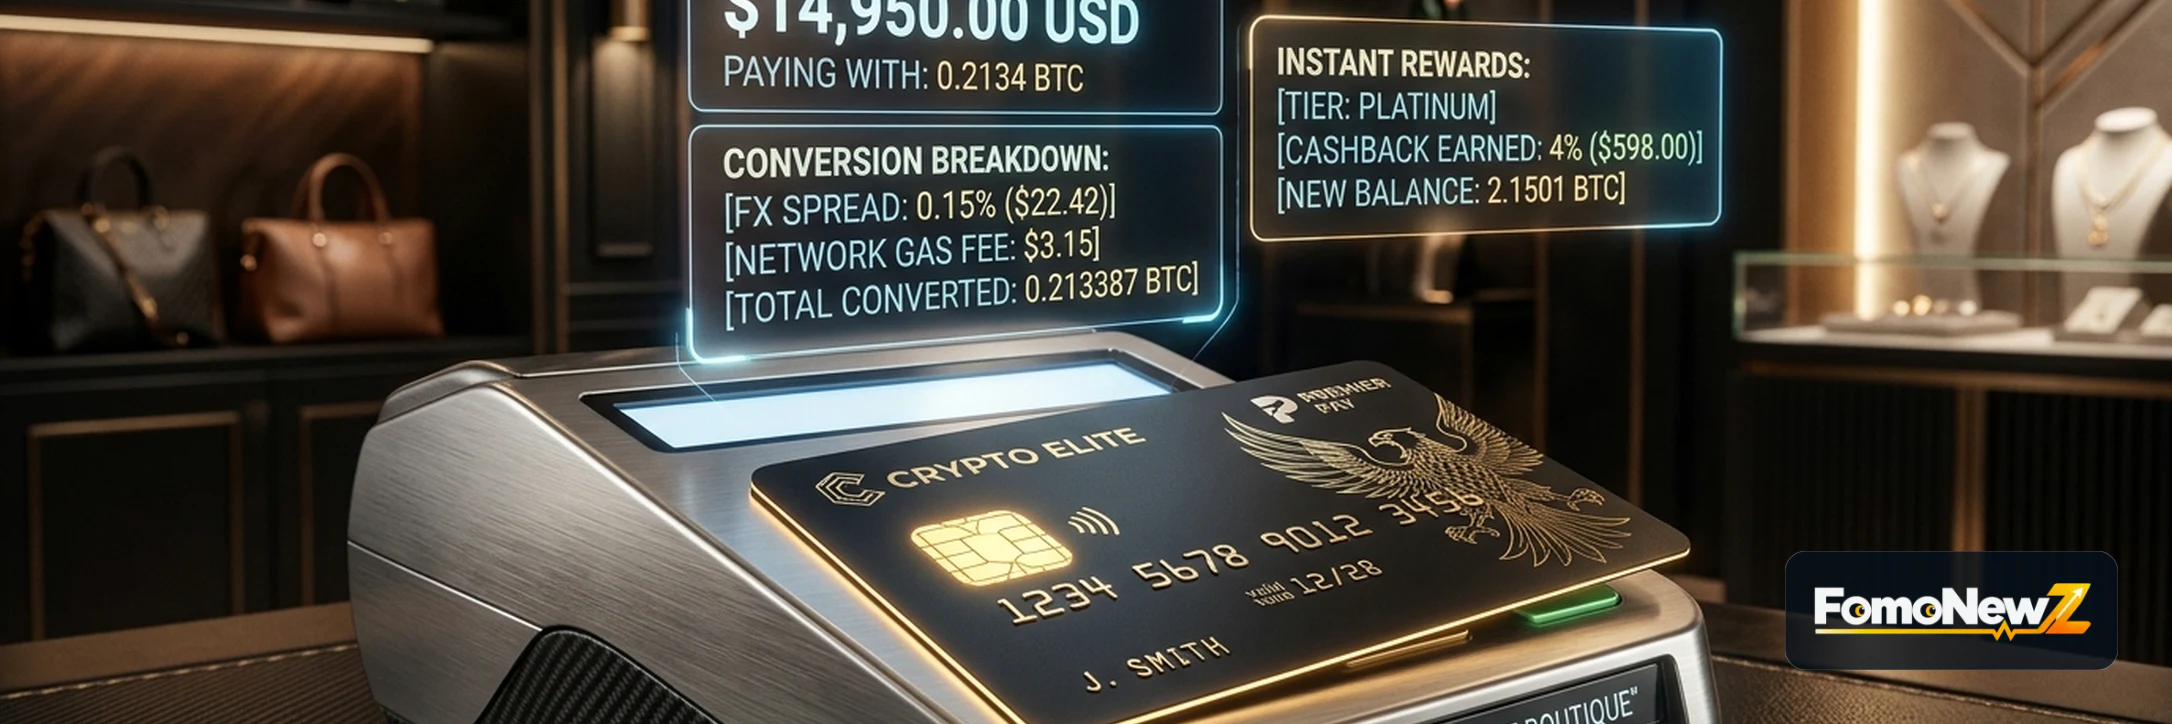
- Real-Time Crypto Debit Cards: The user maintains a balance in cryptocurrency (such as BTC, ETH, or USDT). When the physical card is tapped, the card processor automatically liquidates the exact satoshi or token fraction into local fiat currency in real time at the point of sale.
- Collateralized Crypto Credit Cards: The card operates as a true revolving line of credit. The user deposits cryptocurrency as collateral into a custodial account (for example, at an 50% loan-to-value ratio). When purchases are made, the user borrows fiat currency from the issuer, repaying the balance monthly without disposing of their cryptocurrency.
| Feature | Prepaid Crypto Card | Real-Time Crypto Debit | Collateralized Crypto Credit |
|---|---|---|---|
| Balance Source | Pre-funded fiat account | Active crypto wallet balance | Borrowed fiat credit line |
| Conversion Timing | Manual, prior to transaction | Automated at swipe time | None (unless liquidated) |
| Tax Implications | Tax event on manual sale | Tax event on every single purchase | No tax event during routine borrowing |
| Liquidation Risk | None | None | High if collateral value drops |
| Credit Score Impact | None | None | Potential reporting on default |
Chapter 02
Point-of-Sale Conversion & The Two-Message Clearing Rail
When you tap a crypto debit card at a supermarket terminal, the merchant does not receive cryptocurrency. The transaction undergoes a sophisticated high-speed dual-message clearing sequence completed in under 2 seconds:
1. Authorization Request (ISO 8583): The merchant terminal transmits an authorization message through the card network (Visa or Mastercard) to the issuer-processor (such as Marqeta, Baanx, or Rain).
2. Liquidity API Query: The issuer-processor fires an API webhook to the cryptocurrency custodian to check if the user holds sufficient balance.
3. Spread Lock & Hold: The custodian quotes an instantaneous bid price, locks in the conversion spread, liquidates the necessary cryptocurrency, and places a temporary fiat authorization hold on the account.
4. Authorization Approval: An authorization approval code is sent back through the payment network to the merchant terminal, completing the transaction.
5. Clearing and Batch Settlement: 24 to 48 hours later, the card network processes the net settlement. The card issuer transfers native fiat currency to the merchant's acquiring bank. The merchant never touches cryptocurrency and assumes zero digital asset volatility risk.
Chapter 03
Fees, Spreads, and the True Cost of Spending Crypto
Card providers frequently advertise 'zero percent transaction fees,' but consumers must understand the economic spread baked into every payment:
- Conversion Spread Markup: The primary profit center for crypto debit cards is the bid-ask spread. When converting BTC or ETH into fiat at checkout, the rate applied is often 0.5% to 2.5% below the prevailing global market spot price.
- Foreign Exchange (FX) Margins: Spending in a currency different from your default card denomination can incur cross-border foreign exchange surcharges of 1% to 3%.
- ATM Withdrawal Fees: While standard domestic ATM cash withdrawals may have a monthly free quota, subsequent withdrawals or international ATM usage carries fixed fees plus percentage surcharges.
- Inactivity & Issuance Costs: Some providers assess a one-time physical card production fee (especially for premium metal cards) and charge recurring monthly inactivity penalties if the card remains dormant.
Chapter 04
Jurisdictional Availability, Licensing & KYC Verification
Because crypto cards bridge public blockchains with sovereign banking rails, issuers operate under rigorous international anti-money laundering (AML) and banking regulations:
- Regulatory Licensing: In the European Union and United Kingdom, card programs partner with licensed Electronic Money Institutions (EMIs) authorized by the FCA or national central banks. In the United States, issuers must register as Money Services Businesses (MSBs) with FinCEN and comply with individual state money transmission regulations.
- Identity Verification (KYC/AML): Anonymous crypto cards with meaningful spending limits no longer exist under compliant regulatory regimes. Users must complete Customer Due Diligence (CDD), providing government identification, proof of residential address, and for higher volume tiers, source-of-wealth documentation.
- Regional Restrictions: Card programs are typically geographically ring-fenced. A card issued in the EEA cannot be shipped to US or Canadian residents, and sanctioned regions are strictly blocked at the BIN (Bank Identification Number) routing level.
Chapter 05
Taxation Realities & Liquidation Threat Vectors
Before using a cryptocurrency card for daily expenditures, cardholders must evaluate two critical operational risks:
- Capital Gains Tax on Daily Purchases: In the United States (under IRS Notice 2014-21), the United Kingdom (HMRC), and most European jurisdictions, cryptocurrency is legally classified as property or a capital asset. Every time you buy a $4 coffee with appreciated Bitcoin via a crypto debit card, you trigger a reportable capital gains tax event. The difference between your original acquisition cost basis and the fair market value at swipe time must be calculated and declared on annual tax filings.
- Credit Card Liquidation Cascades: On collateralized crypto credit cards, your borrowing power is governed by Loan-to-Value (LTV) limits. If market prices collapse abruptly (a 'flash crash'), your collateral value can breach maintenance thresholds. If you do not deposit additional collateral immediately, the protocol or custodian will automatically liquidate your collateral at market lows to repay the borrowed fiat balance.