Chapter 01
A card is not a single global product
A single global brand may market a crypto payment card worldwide, but the underlying legal product varies dramatically across jurisdictions. In one region, the card may operate as a prepaid debit product backed by an electronic money institution; in another, it operates as a revolving line of credit issued by a chartered partner bank. The issuing corporate entity, supported fiat base currencies, card network rails (Visa or Mastercard), ATM withdrawal fee schedules, and cashback reward eligibility change based on the cardholder's country of residence and verified KYC tier.
Start your evaluation with the specific legal card agreement applicable to your jurisdiction rather than marketing materials published for international audiences. Identify whether the card operates under a debit model—converting cryptocurrency to fiat currency at the exact moment of transaction authorization—or a collateralized credit model, where card spending incurs a debt balance secured against deposited digital assets. The distinction carries profound financial implications: debit conversions may trigger capital gains tax reporting events upon every merchant swipe, whereas credit models introduce liquidation risk if collateral valuations decline.
Chapter 02
Compare the complete multi-layer cost of payment
Assessing the real financial cost of a crypto debit card requires examining every layer of the transaction pipeline rather than relying on a headline "zero annual fee" claim. Every point-of-sale transaction involves three distinct pricing stages:
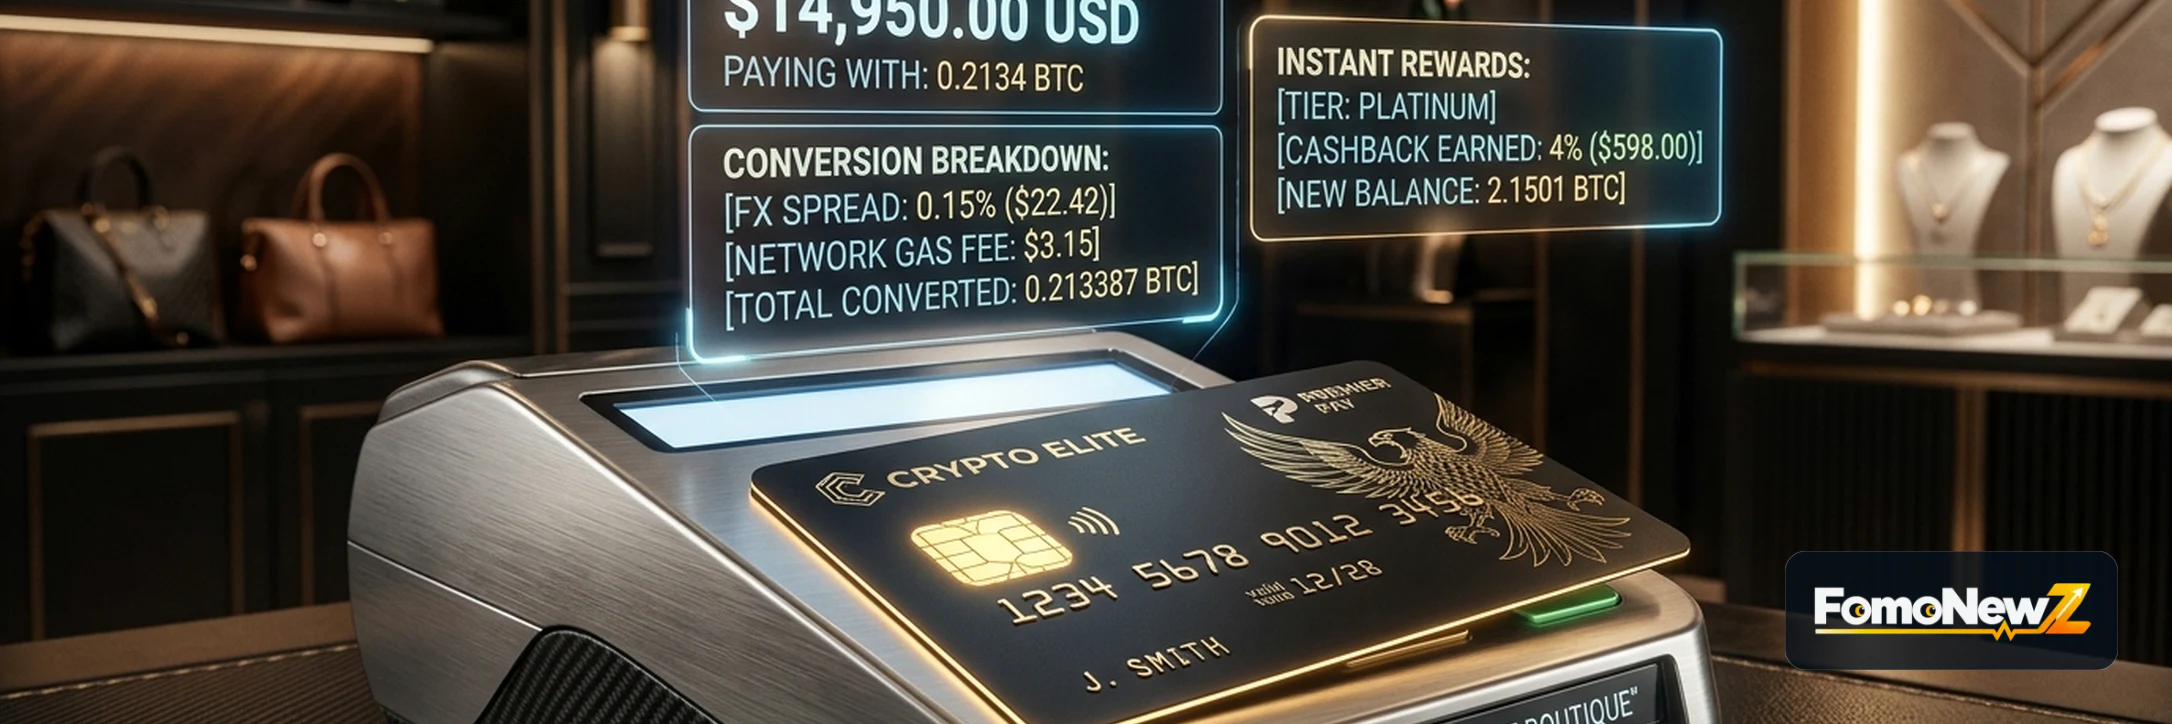
1. The Crypto-to-Fiat Conversion Spread: When digital assets are liquidated to fund a purchase, providers frequently apply an internal exchange spread of 0.5% to 2.5% above prevailing institutional spot prices. A card offering 2% cashback is financially neutral or negative if the user pays a 2% hidden conversion markup on the liquidated cryptocurrency. 2. Foreign Exchange (FX) and Cross-Border Markups: Spending in a currency other than the card's native settlement denomination often incurs network conversion surcharges ranging from 1% to 3%, particularly outside standard banking operating hours. 3. ATM and Maintenance Charges: Most programs impose tiered fee structures on cash withdrawals: offering modest monthly allowances (such as $200 to $500) before levying 2% percentage charges on subsequent transactions, on top of local ATM operator surcharges.
Calculate the total delivered cost for your typical spending profile. If you intend to fund everyday purchases using stablecoins like USDC, choose cards that support direct 1:1 fiat redemption without conversion markups.
Chapter 03
Scrutinize rewards programs, staking tiers, and exclusion lists
Cashback rewards are the primary feature used to market crypto payment cards, yet they frequently come with substantial commercial strings attached. Many top-tier cashback percentages (ranging from 3% to 8%) require cardholders to purchase and lock up substantial amounts of the provider’s proprietary utility token for six months or longer. If the token's market price declines during the lockup period, the capital loss can easily exceed years of accumulated spending rewards.
Furthermore, card issuers enforce extensive Merchant Category Code (MCC) exclusions. Utility bills, insurance premiums, mortgage payments, tax remittances, and government services are almost universally excluded from earning reward points. Monthly cashback caps also limit total earnings, meaning an advertised 5% reward rate may be capped at $50 per calendar month. Evaluate rewards on an effective, unencumbered basis rather than marketing ceilings.
Chapter 04
Custodial counterparty risks and consumer protections
Digital assets deposited to fund a crypto debit card reside in the custody of the card operator or its partner depository. Unlike traditional commercial bank deposits protected by government insurance programs (such as FDIC in the United States or FSCS in the United Kingdom), crypto card account balances are not automatically protected against issuer insolvency. If a platform experiences operational insolvency or freezes withdrawals, cardholder funds may become illiquid unsecured creditor claims.
Mitigate custodial exposure by maintaining only the working balance required for near-term spending. Never treat a crypto card account as a long-term savings depository. Before travelling internationally, execute a small trial transaction to confirm currency conversion rules and fraud monitoring thresholds. Review our crypto-card research desk and stablecoin payment settlement guide to evaluate verified product records and regional compliance frameworks.
Chapter 05
Card issuing structures: custodial debit vs self-custodial smart contracts
Cryptocurrency debit cards bridge decentralized digital assets with global legacy payment networks (Visa and Mastercard) through two distinct structural models:
1. Custodial Debit Cards: The cardholder deposits cryptocurrency directly into a centralized exchange or regulated fintech custodian. The custodian maintains custody of the private keys. When the user swipes their card at a point-of-sale (POS) terminal, the exchange instantly executes a market sell order converting the required crypto balance into local fiat currency, routing the fiat payment across the payment rail to the merchant. 2. Self-Custodial Smart Contract Cards: The user retains custody of their funds in an on-chain smart contract wallet utilizing Account Abstraction (ERC-4337). The user approves an authorized payment processor contract to pull collateralized stablecoins (e.g., USDC) only upon receipt of a cryptographically signed authorization message from the card network. If the card processor suffers a security compromise, the user's primary capital remains secured on-chain.
Chapter 06
Total cost analysis: interchange, foreign exchange spreads, and liquidation markup
Evaluating the true financial efficiency of a crypto debit card requires auditing the cumulative fee stack incurred across every transaction:
Total Cost = Liquidation Spread + Foreign Exchange (FX) Markup + Interchange Fee + ATM Surcharge
- Conversion Spread Markup: When crypto is converted to fiat at the moment of payment, platforms routinely apply a bid-ask spread markup ranging from 0.50% to 2.0% above prevailing spot rates.
- Foreign Transaction Fees (FX): Making purchases in a currency different from the card's native settlement fiat currency often triggers cross-border interchange markups of 1.5% to 3.0%.
- Token Reward Degradation: Advertised cashback rewards (e.g., "5% cashback") are frequently paid in proprietary platform utility tokens subject to high volatility, staking lockup requirements, and secondary market slippage when redeemed. Users should calculate net annualized rewards by subtracting conversion spreads and staking opportunity costs from advertised gross cashback percentages before locking up capital.
Cardholders should also evaluate tax implications: in many jurisdictions, spending cryptocurrency through a debit card constitutes a taxable disposal event. Every point-of-sale transaction triggers capital gains or losses calculations based on the fair market value of the liquidated asset relative to its acquisition cost basis, requiring automated transaction tracking software to prevent severe accounting errors at tax filing deadlines. Savvy cardholders prioritize cards offering direct stablecoin settlement and zero conversion markups on domestic point-of-sale transactions.