Chapter 01
The dual-rail architecture: Connecting blockchains to legacy card networks
Every modern cryptocurrency card operates across two fundamentally distinct financial networks: public or private blockchain ledgers on the user side, and legacy merchant acquiring networks like Visa or Mastercard on the merchant side. Because brick-and-mortar merchants cannot accept unconfirmed, volatile blockchain transactions at point-of-sale terminals, specialized financial infrastructure bridges the gap.
When a cardholder taps their physical plastic card or smart device at a checkout terminal, the merchant POS terminal does not interact with the Bitcoin or Ethereum network. Instead, the terminal broadcasts a standard ISO 8583 authorization message across the card scheme network to an issuing bank partner.
The issuing bank routes the authorization inquiry to the crypto card program manager. Within 800 to 1,200 milliseconds, the card platform must evaluate the user's available digital asset balance, execute a real-time price conversion or reserve lock, and return an authorization approval or decline code back across the payment rails.
Chapter 02
Real-time liquidation versus pre-funded stablecoin balances
Crypto cards handle asset conversion through one of two primary architectural models: real-time programmatic liquidation or pre-funded fiat and stablecoin balances. Each model introduces distinct operational tradeoffs regarding volatility slippage, liquidity requirements, and user experience.
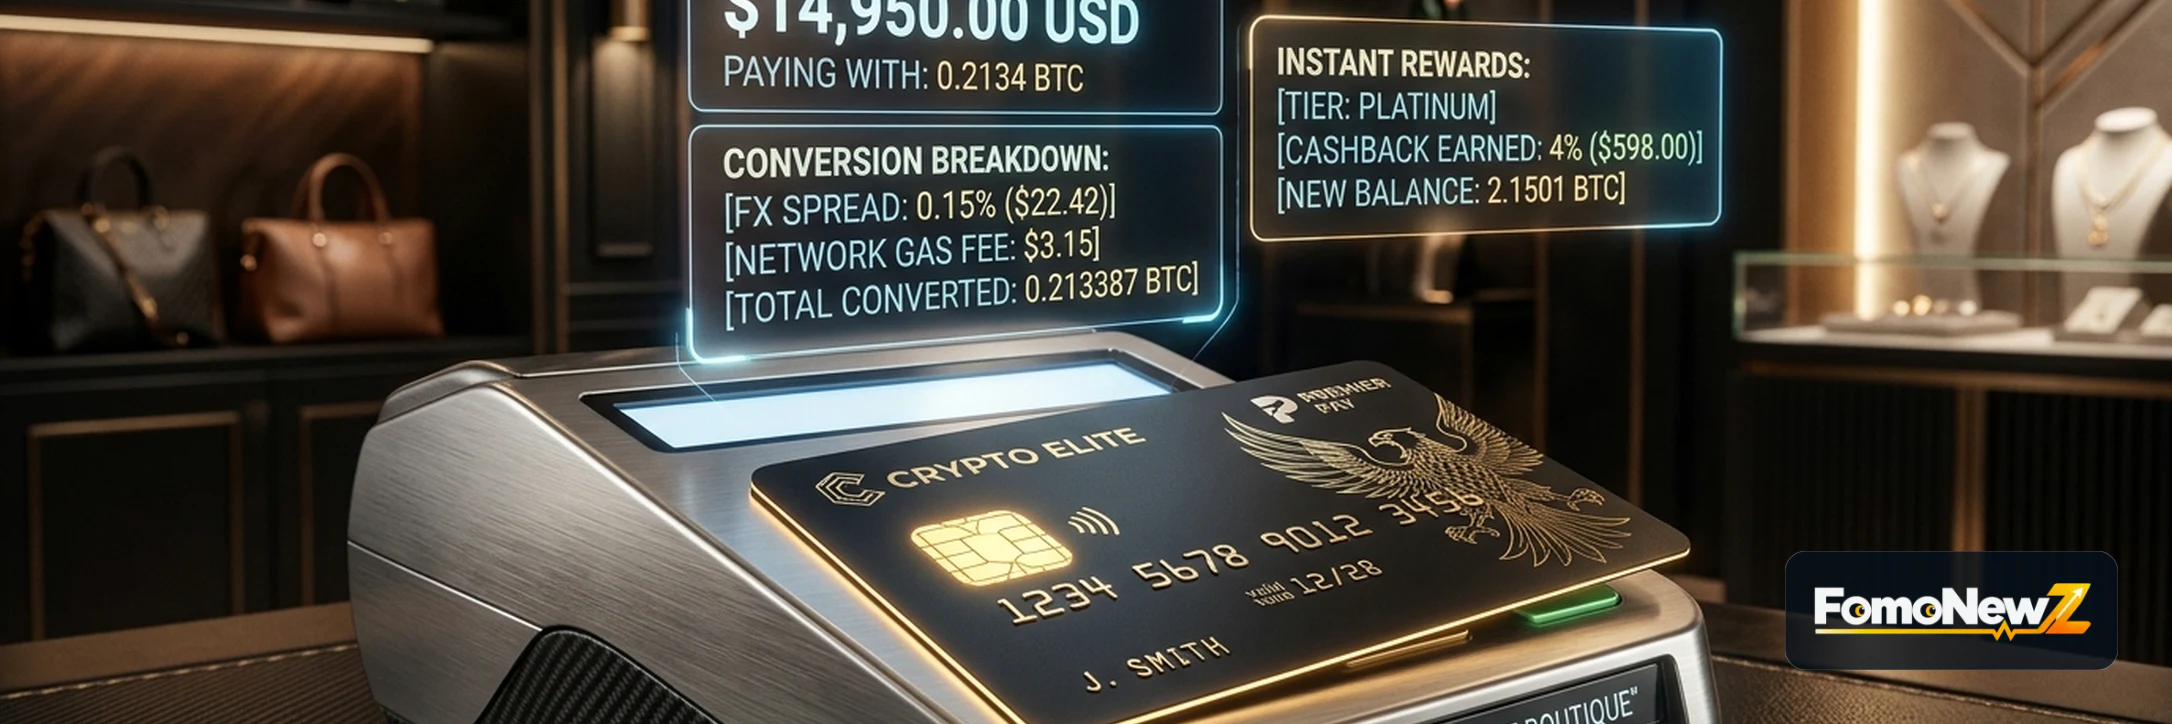
In a real-time programmatic liquidation model, the user maintains a balance in volatile assets such as Bitcoin, Ethereum, or Solana. At the exact moment of swipe authorization, the platform's internal matching engine or market maker partner executes an immediate spot market liquidation, converting the required cryptocurrency amount into local fiat currency to satisfy the authorized purchase amount.
While real-time liquidation provides convenience by allowing users to spend directly from investment portfolios, it exposes purchases to exchange spreads, network slippage, and immediate capital gains taxable events. Conversely, pre-funded stablecoin models (such as cards holding pure USDC or USDT) lock balances at 1:1 parity with the US dollar, eliminating conversion volatility and minimizing spread markups at checkout.
Chapter 03
Interchange fee economics and corporate revenue distribution
Understanding the economic sustainability of crypto card programs requires dissecting the interchange fee structure. When a consumer completes a card transaction, the merchant pays a Merchant Discount Rate (MDR) averaging between 1.5% and 3.0% of the gross transaction value, depending on jurisdiction and card tier.
This merchant fee is split between three primary stakeholders: the payment network (Visa or Mastercard scheme fees), the acquiring processor managing merchant integration, and the card issuer (interchange fee). The interchange fee represents the largest portion of this fee pool, often ranging from 1.0% to 2.2% on international or premium rewards cards.
Crypto card issuers utilize this interchange revenue stream to fund consumer cashback programs, customer support operations, and compliance infrastructure. Programs offering cashback percentages exceeding the underlying interchange rate must subsidize rewards through native token inflation, custodial staking yields, or venture capital reserves.
Chapter 04
Authorization holds, settlement cycles, and foreign exchange markups
A crucial technical distinction often confusing new cardholders is the difference between transaction authorization and final financial settlement. When you purchase an item, the card network places a temporary authorization hold on your account to guarantee funds to the merchant.
For transactions involving hospitality, car rentals, or automated fuel dispensers, the authorization hold frequently exceeds the final transaction amount by 15% to 20% to account for tips, incidental damages, or tank fills. On volatile crypto balances, this hold locks a larger quantity of cryptocurrency than expected until settlement clears 24 to 72 hours later.
During final settlement, the issuing bank transfers fiat funds through interbank clearing systems (such as Fedwire or SEPA) to the acquiring bank. If a purchase was conducted in a foreign currency, cardholders must scrutinize whether their issuer settles at the benchmark Visa or Mastercard interbank rate or tacks on an additional foreign transaction (FX) spread fee of 1.5% to 3.0%.
Chapter 05
Custodial models and counterparty solvency risks
Most mainstream crypto cards operate under a custodial architecture where the card provider or its regulated trust partner holds legal custody of customer assets. While this custody enables sub-second transaction authorizations, it exposes cardholders to operator counterparty risk and balance freezing in the event of insolvency.
Emerging decentralized and non-custodial crypto card protocols utilize smart contract escrow accounts or account abstraction (ERC-4337) to maintain on-chain user ownership until the moment of authorization. Under these frameworks, users retain cryptographic custody of their private keys, authorizing specific spending allowances through timed session keys or pre-signed permit approvals.
Regardless of which custody model you select, operational prudence requires never treating a crypto debit card account as a primary long-term savings vault. Best security practice mandates keeping only operational spending reserves in card wallets while maintaining the bulk of long-term digital wealth in audited cold storage.